ECB Raises Rates as Energy Shock Keeps Euro-Area Inflation Elevated
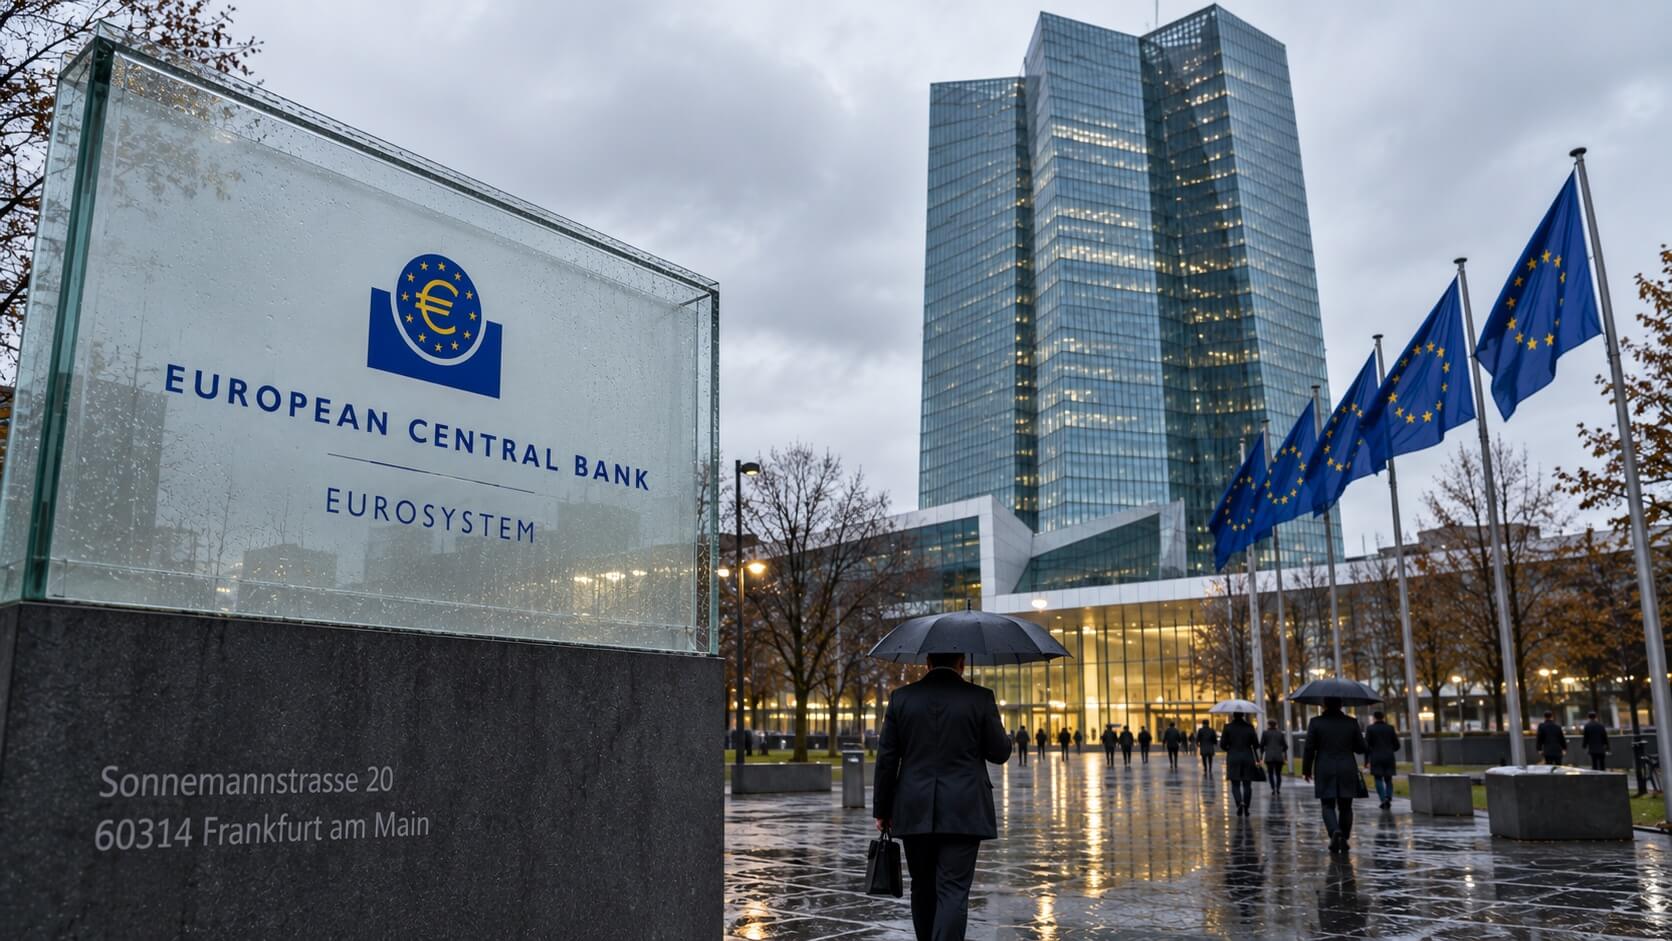
The European Central Bank has raised its three key interest rates by 25 basis points, responding to an inflation outlook that has become more difficult as higher energy costs feed through the euro-area economy. The move takes the deposit facility rate to 2.50%, the main refinancing rate to 2.65% and the marginal lending rate to 2.90%, effective from 16 September.
The decision was widely anticipated, but the message around it matters. The ECB said inflation is likely to remain above its 2% target for an extended period, while stressing that it has not committed to a fixed path for future rates. That combination leaves markets focused on incoming inflation data, energy prices and the resilience of economic activity rather than on a predetermined tightening cycle.
The backdrop is an unusual mix of stronger headline inflation and relatively contained underlying price pressure. Eurostat estimated that euro-area annual inflation rose to 3.3% in August from 2.9% in July. Energy inflation accelerated to 14.3%, while inflation excluding energy was 2.2%. The distinction is important because it shows that the latest rise in the headline rate is being driven mainly by the energy shock rather than by a broad acceleration across all categories.
Why the ECB moved now
The ECB has been clear that the conflict in the Middle East is creating renewed inflation pressure through energy markets. Higher oil and natural gas prices can affect transport, industrial production and household energy bills directly, but policymakers are also watching for second-round effects through wages and the prices of other goods and services.
September staff projections put average headline inflation at 3.0% in 2026, 2.5% in 2027 and 2.1% in 2028. The 2027 and 2028 forecasts were revised higher from June. Inflation excluding energy and food is projected at 2.5% this year, 2.6% in 2027 and 2.3% in 2028, suggesting that the ECB expects the return to target to be gradual rather than immediate.
At the same time, the growth picture has held up somewhat better than the ECB expected three months ago. The bank now projects euro-area GDP growth of 0.9% in 2026 and 1.4% in 2027, both revised higher from June, followed by 1.5% in 2028. That resilience gives policymakers more room to respond to inflation, even as higher energy costs pose a risk to future activity.
A supply shock creates a difficult policy trade-off
Energy-driven inflation presents central banks with a difficult balance. Raising interest rates cannot directly increase oil or gas supply, but policymakers may still tighten financial conditions if they are concerned that a temporary energy shock could become embedded in inflation expectations, wage negotiations or broader price-setting behaviour.
The ECB acknowledged that uncertainty remains unusually high. Its September projections include alternative scenarios for the Middle East conflict because the economic effect depends heavily on how long the disruption lasts, how severe it becomes and how much of the energy shock passes through to the rest of the economy. Under the baseline, inflation gradually moderates, but the ECB also modelled materially worse outcomes if the shock intensifies.
This helps explain why the Governing Council retained a meeting-by-meeting approach. The bank said future decisions will depend on the inflation outlook, underlying inflation and the strength of monetary policy transmission, rather than on a preset sequence of rate changes.
European bonds and equities react to a tighter rate outlook
The policy decision reinforced a broader rise in European borrowing costs. Germany’s 10-year government bond yield moved to its highest level since 2011 after the announcement, according to Reuters. Higher sovereign yields can filter through to corporate financing, mortgages and equity valuations, making the bond market an important part of the monetary-policy transmission story.
European equities also came under pressure. The STOXX 600 closed 0.7% lower at 635.97 on 10 September, its lowest level since early July, as investors assessed the prospect of further tightening alongside elevated energy prices. Reuters reported that traders were pricing around 60 basis points of additional ECB increases by the April 2027 meeting after the decision, although market pricing can change quickly as new data arrive.
For the euro, the policy backdrop is also important because relative interest-rate expectations remain a major driver of currency markets. The ECB’s stance now sits alongside shifting expectations for the Federal Reserve and other major central banks, making inflation surprises and rate guidance particularly relevant for EUR pairs.
What traders are watching
- Energy prices, particularly crude oil and European natural gas, for signs that the inflation shock is easing or becoming more persistent.
- Euro-area inflation data, including the split between headline inflation and measures that exclude volatile energy and food components.
- ECB communication on whether inflation risks are spreading beyond energy into wages and services.
- German and wider euro-area government bond yields, which are a direct gauge of changing rate expectations and financial conditions.
- EUR pairs and European indices as markets reassess the relative policy path between the ECB and other major central banks.
- Growth indicators such as PMIs, industrial activity and consumer demand, which will help show how higher energy costs and tighter financing conditions are affecting the real economy.
The next phase depends on transmission, not one meeting
The September decision confirms that the ECB is prepared to respond when an external energy shock threatens its medium-term inflation objective. It does not, however, settle the question of how far rates will ultimately need to rise. Headline inflation is elevated, but underlying inflation has been more stable and wage growth has shown signs of moderation, while higher bond yields are already tightening financial conditions.
That leaves the policy outlook sensitive to the interaction between energy markets and domestic inflation. If the shock remains concentrated in energy and fades, the case for continued tightening could look different from a scenario in which higher costs spread more broadly through wages and services. For markets, that distinction is likely to remain central to the euro-area rates story in the months ahead.
Frequently Asked Questions
The ECB raised all three key interest rates by 25 basis points. From 16 September, the deposit facility rate will be 2.50%, the main refinancing rate 2.65% and the marginal lending rate 2.90%.
The ECB said the Middle East conflict continues to create inflation pressure, particularly through energy prices. It wants to prevent the shock from keeping inflation above its 2% target for longer or spreading into broader price and wage setting.
Eurostat’s flash estimate put annual euro-area inflation at 3.3% in August 2026, up from 2.9% in July. Energy inflation was 14.3%, while inflation excluding energy was 2.2%.
The ECB has not committed to a particular rate path. It said future decisions will remain data-dependent and will be taken meeting by meeting, based on the inflation outlook, underlying inflation and the strength of policy transmission.